Blog

  • U.S. Home Prices Ease Across Major Metros

    U.S. Home Prices Ease Across Major Metros

    We're seeing a notable shift in the housing market as Mid-Q3 data shows that price per square foot dropped year-over-year in 36 out of the 50 largest U.S. metro areas. Nationwide, this measure declined by about 2% compared to last year—marking the tenth consecutive month of annual softening. As the quarter closed, momentum slowed even further, with many sellers adjusting their asking prices more aggressively to better align with buyers’ expectations. High mortgage rates have played a significant role, especially in areas that saw rapid growth during the pandemic, leading sellers to meet buyers somewhere in the middle. According to economists, a number of cities that experienced boom-level appreciation are now giving back some of those pandemic-era gains, aided by inventory levels that remain above pre-pandemic norms.

    As someone who guides clients through both the real estate and mortgage sides of the equation, I keep a close eye on these market dynamics to help you make informed decisions—whether you’re buying, selling, or investing. My goal is always to ensure your experience is smooth, transparent, and tailored to your needs, even as the landscape changes.
  • Innovative Compact Homes Offer Affordable Urban Living

    Innovative Compact Homes Offer Affordable Urban Living

    Have you noticed that new single-family homes are getting smaller, yet the price tags keep climbing? In 2025, the average new U.S. single-family home will be about 2,409 square feet—down 11.6% from ten years ago. But despite the shrinking space, the price per square foot has nearly soared by 72%. As a broker and mortgage professional serving Georgia, Alabama, Tennessee, and Florida, I see firsthand how builders are adapting homes to address rising costs and affordability concerns. My mission is to help you make sense of these shifting trends, offering honest advice and tailored solutions whether you're buying, selling, or investing. Through every market change, I’m committed to guiding you with integrity, clear communication, and a client-first approach.

    Continue to full article

  • The best and worst states for first-time home buyer assistance in 2026

    The best and worst states for first-time home buyer assistance in 2026

    Navigating the path to homeownership for the first time is a big step—and the support you receive can make all the difference. Across the country, states offer very different levels of assistance: some provide generous forgivable loans and grants, while others limit support to repayable aid with stricter terms. These programs can differ in income limits, loan structures, and even include unique benefits like student debt relief. Drawing on my experience in both real estate and mortgage financing throughout Georgia, Alabama, Tennessee, and Florida, I’ve seen how crucial it is to understand the options in your area to make informed decisions. For first-time buyers, knowing where you stand can help you plan ahead and take advantage of the best possible resources on your journey to homeownership.

    Continue to full article

  • Home Prices Rise 2.6% YoY Despite Expanding Inventory

    Home Prices Rise 2.6% YoY Despite Expanding Inventory

    July’s numbers are in: national home prices climbed 2.6% year-over-year, reaching a median of $400,000. Even as inventory grew by 4.4% and home sales rose 2.9%, prices continued their steady upward trend. Price growth looks a little different depending on the property—single-family homes saw a 2.5% increase, condos 2.3%, and townhomes 0.8%.

    As someone who’s spent decades guiding clients through real estate and mortgage decisions across Georgia, Alabama, Tennessee, and Florida, I know how these shifts can impact your plans—whether you’re buying, selling, or investing. My dual expertise in both real estate and lending means I approach every transaction with a clear perspective and a commitment to making the process as straightforward as possible. A changing market can create questions, but with the right guidance and honest, personal attention, there’s always a path forward.

    Continue to full article

  • Why Buyers and Sellers Are Stuck

    Why Buyers and Sellers Are Stuck

    The current real estate market feels like a standstill for many buyers and sellers. With higher mortgage rates, monthly payments are less appealing, prompting more buyers to hold off rather than make offers. We're seeing this reflected in slowing pending sales—fewer people are making the leap from searching to actually moving forward. On the other side, homeowners locked into lower-rate mortgages are understandably hesitant to list their homes and take on higher payments, which means fewer new properties are hitting the market. This creates a unique challenge: buyers are waiting for better affordability, while sellers are reluctant to let go of their low rates, leading to much slower activity overall. Having spent decades in both real estate and mortgage lending, I’ve seen how these moments of gridlock can create uncertainty. My commitment remains to provide honest advice and clear guidance, helping clients make informed decisions—whether you’re considering waiting or moving forward in this market.

  • US Home Prices Face Real Value Erosion

    US Home Prices Face Real Value Erosion

    As someone who’s spent decades guiding clients through both real estate and mortgage decisions, I watch market trends closely—especially those affecting home values and affordability. In Q2 2026, we saw US home prices continue to rise on paper, but after adjusting for inflation, real home values actually declined for the 13th month in a row. While one major federal index showed home prices holding steady month-over-month between mid- and late Q2, and another national index reflected yearly appreciation ticking up from roughly 1% to 1.5%, these gains are still about 2 points behind inflation, which sits around 3.5%. Even with nominal prices staying resilient (as one federal measure has reported positive annual appreciation every quarter since early 2012), buyers are feeling the squeeze. Affordability remains the key challenge, with typical monthly payments on existing single-family homes rising again last quarter. For first-time buyers especially, that means more pressure on the budget. My approach is always to provide honest, clear advice—helping you understand not just the numbers, but what they mean for your real-life decisions. Wherever you are on your real estate journey, thoughtful guidance can make all the difference.

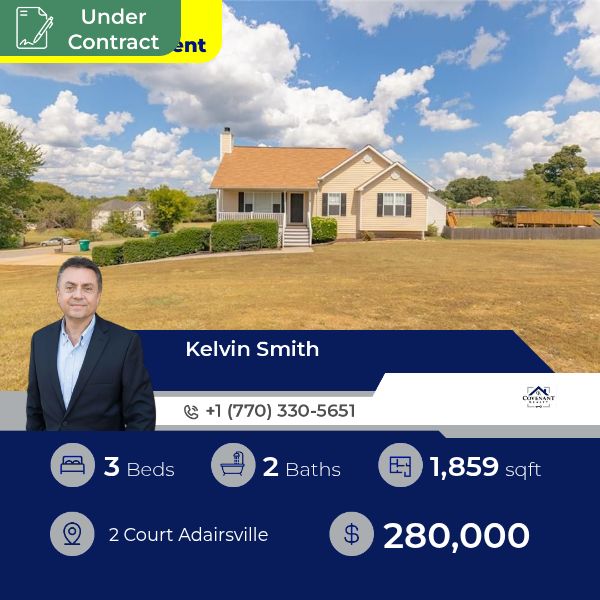
  • Imagine stepping into a raised ranch on a corner lot with three bedrooms, two baths, new flooring, vaulted ceilings, a cozy fireplace, porch, deck, fenced yard, garage and bonus rooms

    Imagine stepping into a raised ranch on a corner lot with three bedrooms, two baths, new flooring, vaulted ceilings, a cozy fireplace, porch, deck, fenced yard, garage and bonus rooms

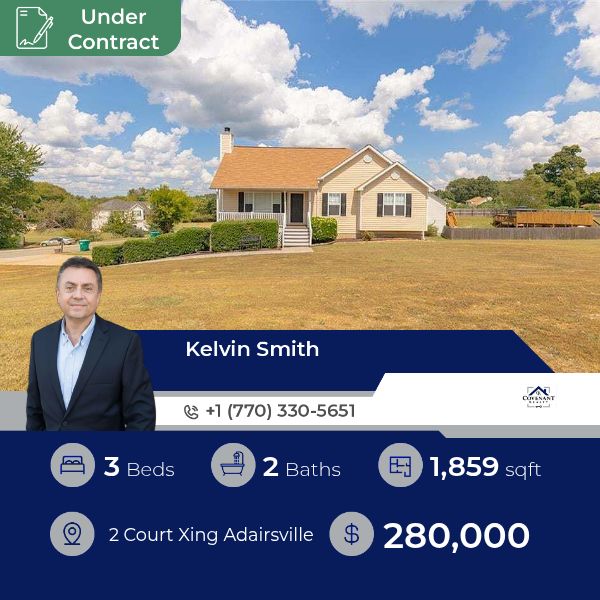
    Welcome home to this charming raised ranch situated on a spacious corner lot! Featuring 3 bedrooms, 2 full bathrooms, and a partially finished basement, this property offers plenty of space for comfortable living and future possibilities. Enjoy your morning coffee on the inviting rocking chair front porch or entertain family and friends on the rear deck overlooking the fenced backyard, perfect for children and pets to play safely. Inside, you'll find all-new flooring, soaring vaulted ceilings, and a warm, welcoming living room complete with a cozy wood-burning fireplace, ideal for relaxing on cool evenings. The functional layout provides both comfort and style throughout. The lower level features a two-car garage and a partially finished basement with two versatile bonus rooms that can be used as a home office, playroom, workout space, or guest area. Don't miss this opportunity to own a wonderful home with great indoor and outdoor living spaces. Call today before this one gets away!

  • Will a cooling labor market keep mortgage rates below 7% in 2026?

    Will a cooling labor market keep mortgage rates below 7% in 2026?

    With recent labor data showing slower job growth and a slight drop in unemployment—mainly due to fewer people participating in the workforce—many are wondering whether mortgage rates will stay below 7% into 2026. As someone who’s spent decades guiding clients through both real estate and mortgage financing across Georgia, Alabama, Tennessee, and Florida, I understand how these shifts can impact your plans, whether you’re buying your first home, selling, or looking to invest. Inflation pressures could linger through 2026, and there’s talk of a possible rate hike in early 2027 as the Federal Reserve keeps its eye on a 2% inflation target, especially with ongoing geopolitical and AI-related uncertainties. My commitment is always to keep you informed with honest, straightforward advice so you can make confident decisions in an evolving market. If you have questions about how these trends might affect your next move, I’m here to help you navigate every step.

    Continue to full article